Table of Contents
Australia has a long renovation culture, and the appetite for upgrading the family home rather than moving has continued through the higher-rate environment of recent years.
Below is a 2026 lens on how renovation lending actually works, the three main paths, and what to do before approaching your lender.
How a renovation loan actually works
At a high level, the lender wants to confirm three things.
The current value of your home (a fresh valuation, sometimes desktop, sometimes physical).
The cost of the renovation (a formal quote from a licensed builder for larger jobs).
The post-renovation value of the home (estimated by the lender from recent comparable sales of renovated homes in your area).
If your equity in the home covers the cost of the renovation (or comes close), and your income services the increased loan at APRA’s buffered rate, you are usually a candidate. If the post-renovation value increases your equity, the LVR position improves.
Three common paths
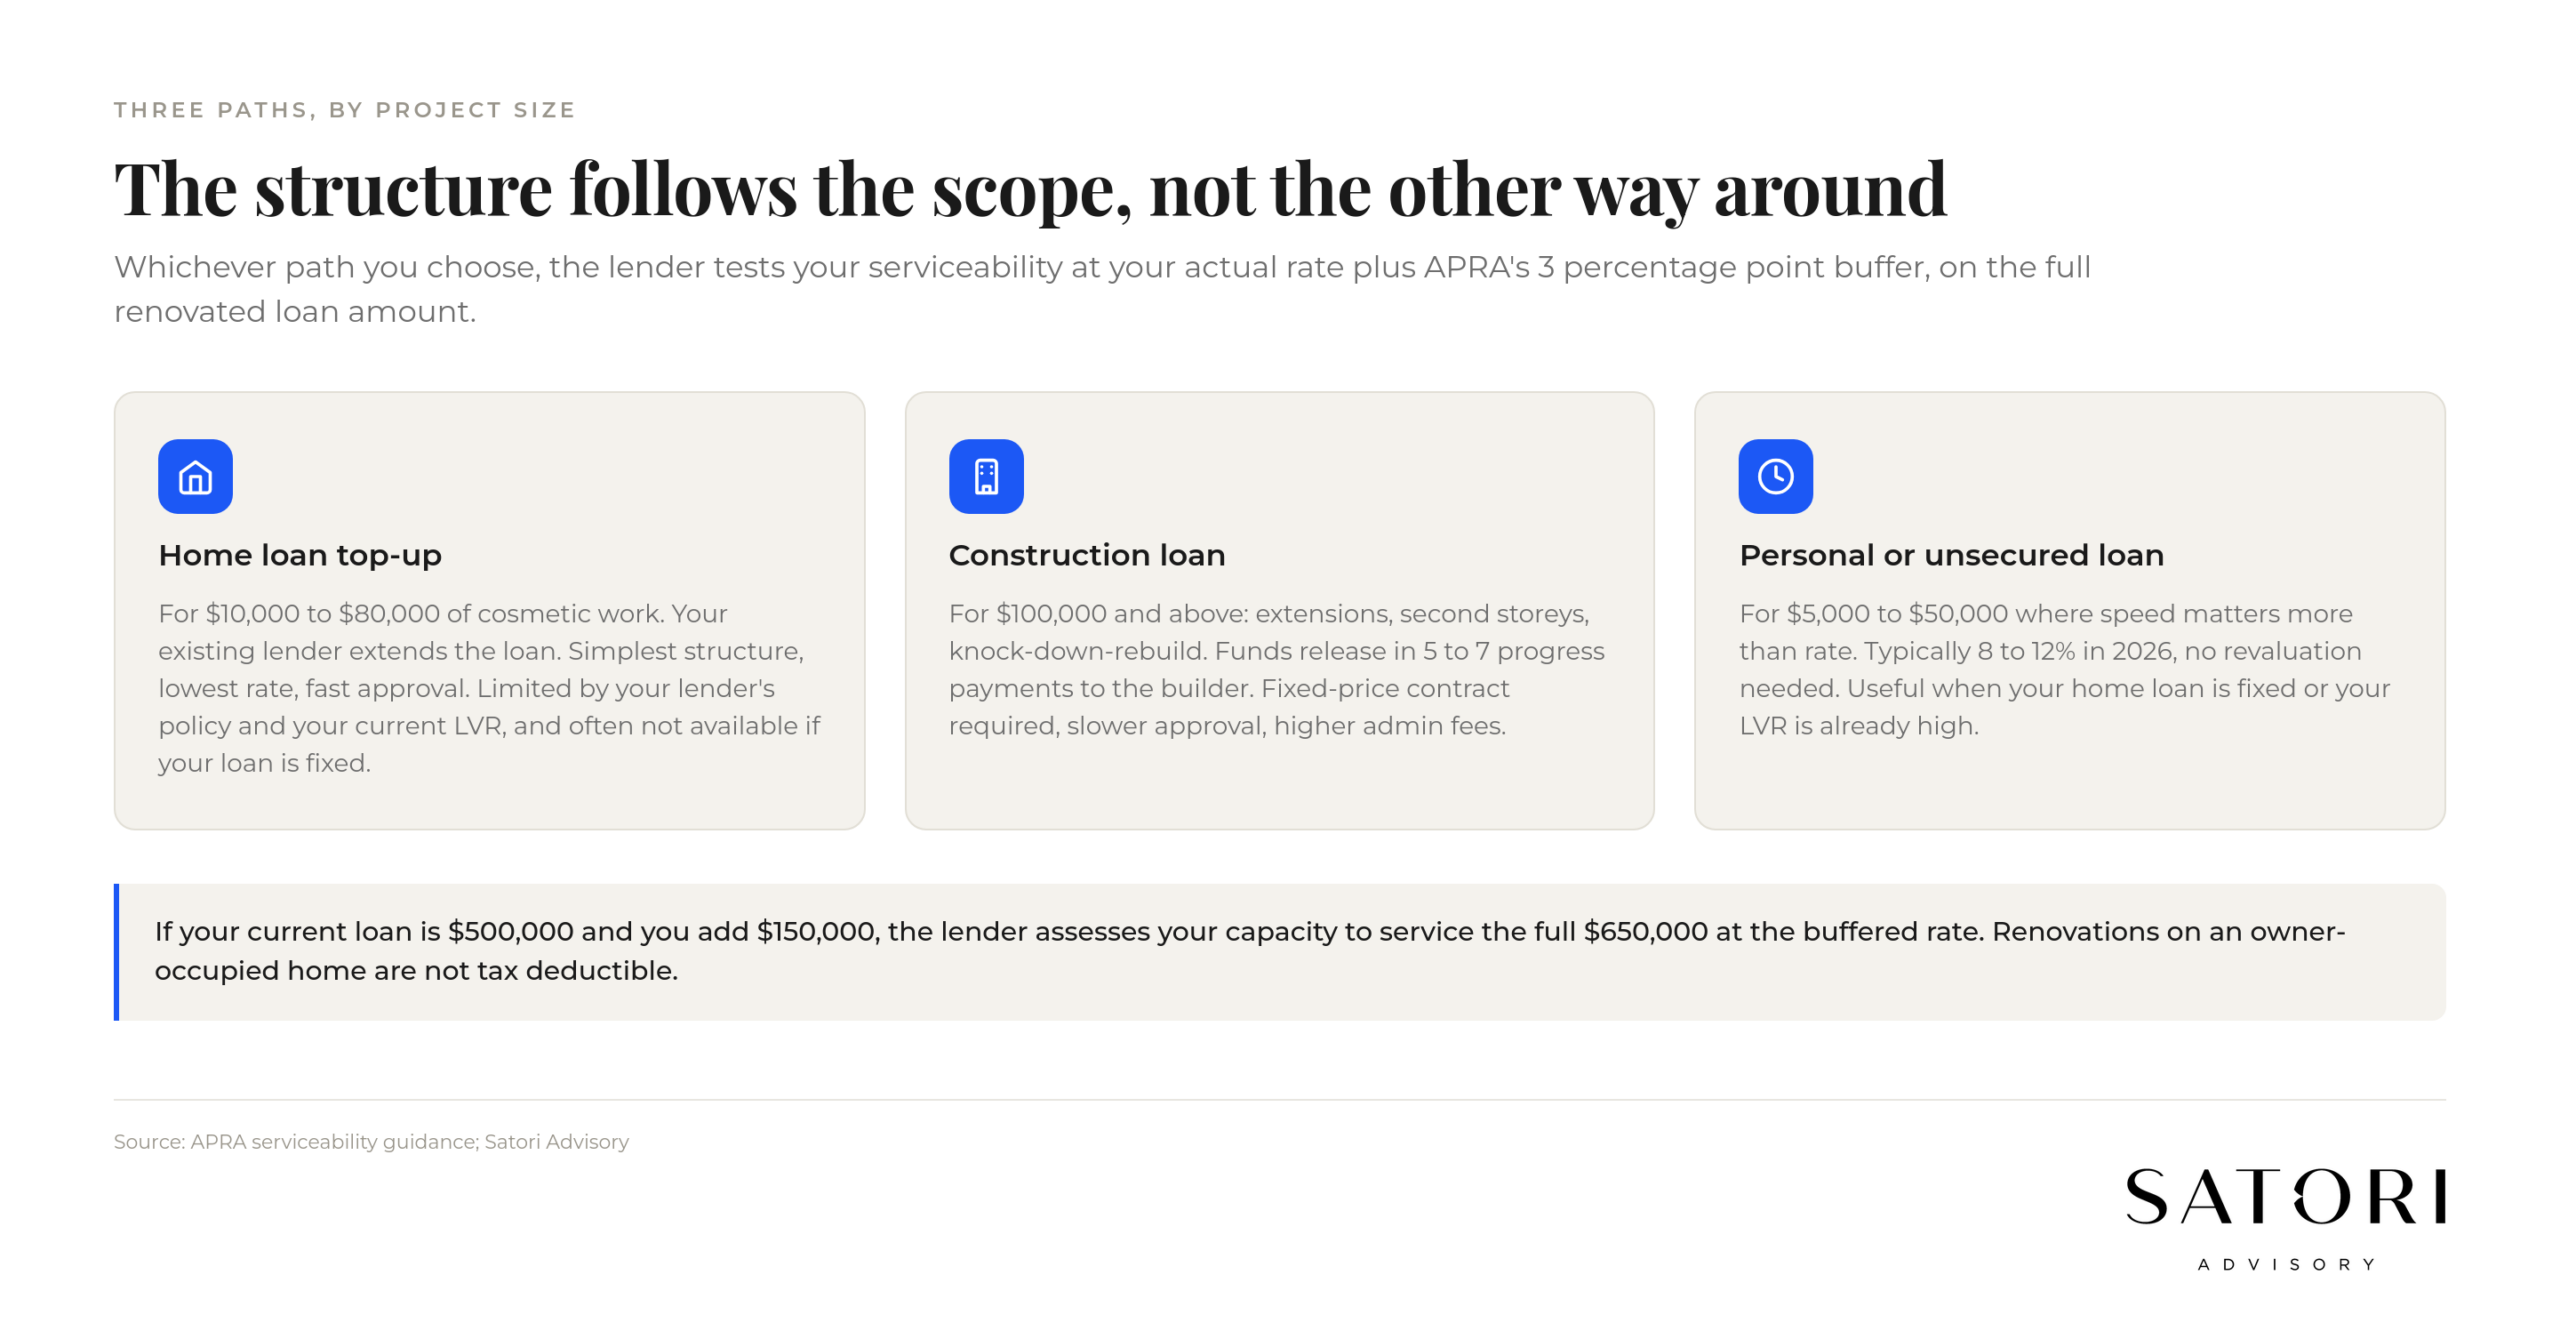
Different project sizes call for different structures. Context: the RBA cash rate sits at 4.35% as of May 2026 (raised 25bp from 4.10% on 5 May 2026), and the RBA’s average rate on new owner-occupier loans was 6.22 per cent in May 2026. Individual lender pricing varies widely by LVR and borrower profile, so compare live offers rather than a headline number.
Home loan top-up
Best for: smaller cosmetic renovations ($10,000 to $80,000) such as kitchens, bathrooms, painting, flooring, deck additions.
How it works: your existing lender extends the loan amount on the existing home loan. No separate facility, no separate rate.
Pros: simplest structure, lowest rate (same as your existing home loan), fast approval, low fees.
Cons: limited by your existing lender’s policy and your current LVR. Lender may not approve if your loan is fixed.
Construction loan
Best for: major structural work ($100,000+) including extensions, second storey additions, full kitchen/bathroom rebuilds, knock-down-rebuild.
How it works: the lender approves the full project cost but releases the funds in stages (typically 5 to 7 progress payments) directly to the builder against signed progress claims. Interest accrues only on the drawn amount.
Pros: structured for large projects, releases payments to the builder cleanly, lender oversight provides discipline.
Cons: more complex documentation (fixed-price contract required, often council approvals before funding), slower approval, higher administrative fees.
Personal loan / unsecured renovation loan
Best for: smaller projects ($5,000 to $50,000) where speed matters more than rate.
How it works: a personal loan from a bank or specialist non-bank lender. Faster approval but higher rate (typically 8-12% in 2026), no security required.
Pros: fast, simple, no need to revalue the home, useful when your home loan is fixed or your LVR is already high.
Cons: higher rate, shorter loan term, fees can be material.
How APRA serviceability applies to renovation loans
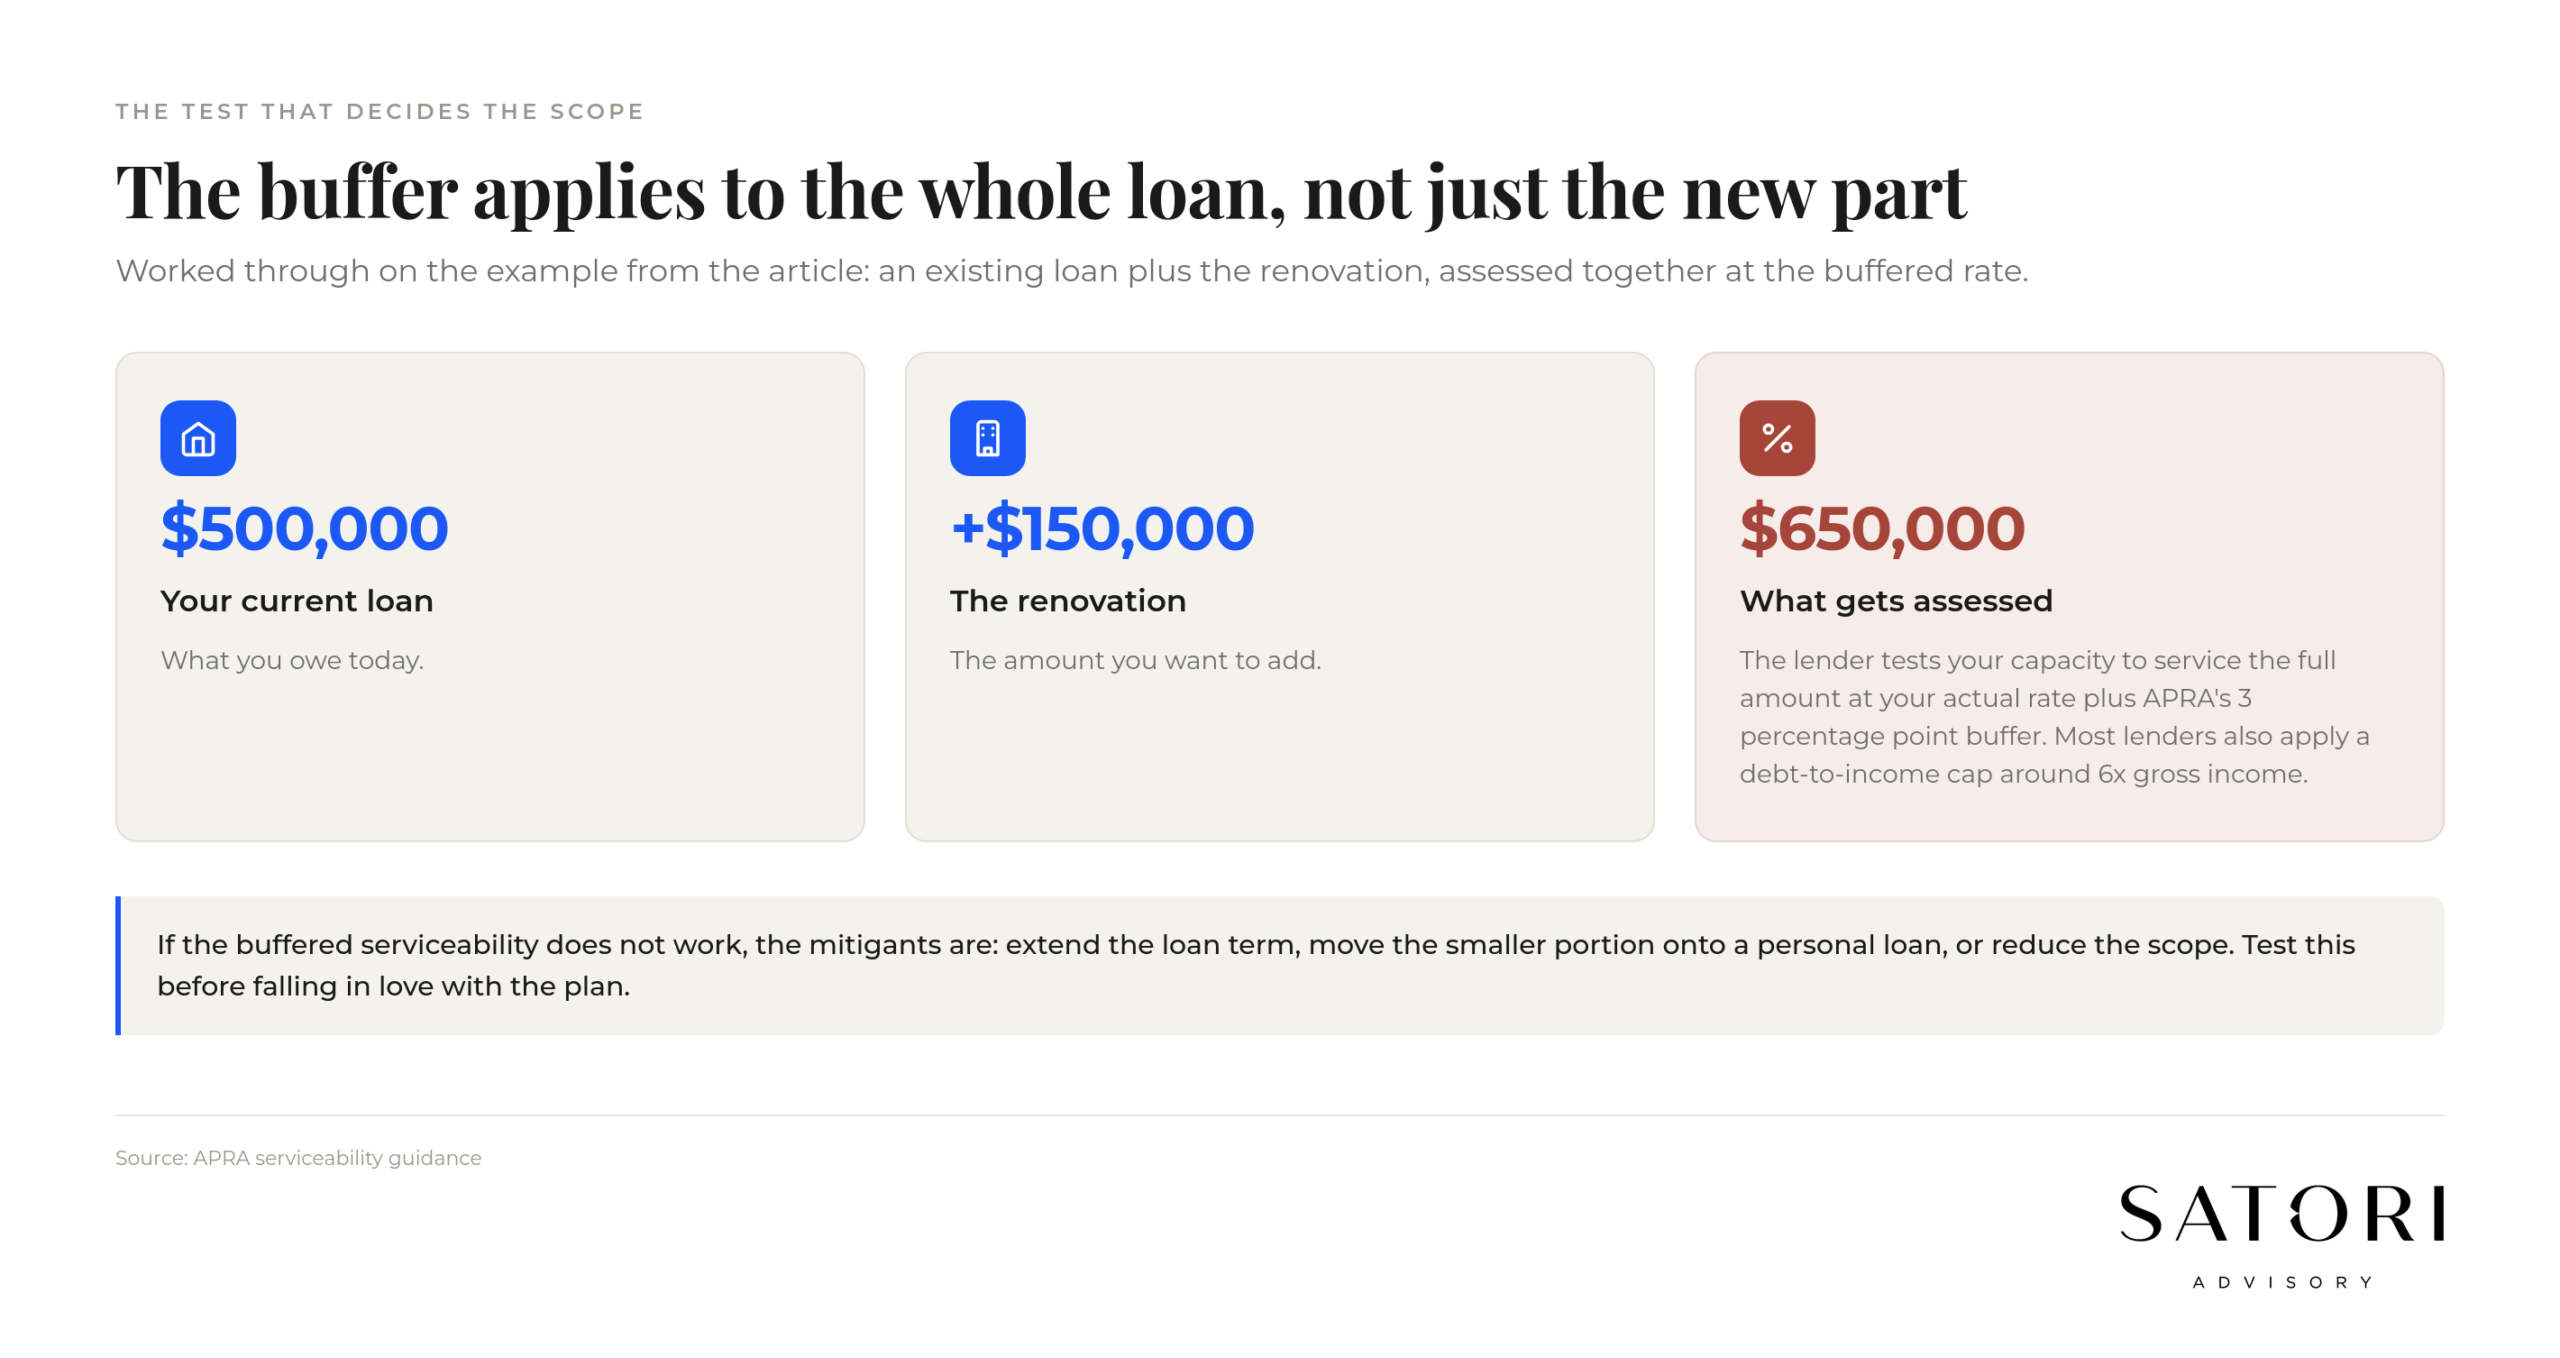
Whichever path you choose, the lender tests your serviceability at your actual rate plus APRA’s 3 percentage point buffer. Most lenders also apply their own debt-to-income (DTI) policy, commonly around 6x gross annual income. Separately, since 1 February 2026 APRA limits banks to writing no more than 20% of new mortgage lending at a DTI of 6 or more.
If your current loan is $500,000 and you are adding $150,000 for the renovation, the lender assesses your capacity to service the full $650,000 at the buffered rate. Approval is not automatic just because you have equity.
If the buffered serviceability does not work, possible mitigants include: extending the loan term, putting the smaller renovation on a personal loan instead of the home loan, or staging the renovation across two financial years.
Does the renovation pay for itself?
Two questions to ask before borrowing.
Will the renovation add more value than it costs? Not all renovations do. The classic value-add jobs (kitchens, bathrooms, adding a bedroom or living space, energy-efficient upgrades) usually return at or above cost. Pool installations, high-spec finishes, and overcapitalising for the suburb usually do not.
How long do you plan to stay? If you plan to sell in two to three years, the renovation needs to deliver value buyers will pay for. If you plan to stay 10+ years, you can prioritise lifestyle over resale value.
Get a real estate agent’s opinion on expected post-renovation value before committing to the scope of work.
Tax considerations
Renovations on your owner-occupied home are not tax deductible.
Renovations on an investment property may be partially deductible (as repairs) or claimed over time (as capital works). The distinction matters and is often misunderstood. Get advice before treating a big spend as a current-year deduction.
If the renovation creates a ‘substantial renovation’ that effectively produces new residential premises, GST can apply on the eventual sale. Worth modelling for investors planning a sell-and-flip after renovation.
How Satori thinks about renovation finance
Through our lending team, we coordinate the renovation finance question with the rest of the financial plan: tax position, super contributions, business cashflow if relevant, and the broader property strategy.
The wrong structure on a renovation loan can lock you into a lender or rate that does not fit your bigger picture. The right structure puts the renovation in place while keeping the rest of the plan intact.
What to do next
Define the scope and get a real quote from a licensed builder.
Estimate the post-renovation value of the home (agent opinion or comparable sales).
Choose the structure (top-up, construction, personal loan) that fits the scope and your equity.
Test serviceability at APRA’s buffered rate before falling in love with the plan.
How Satori Advisory works
At Satori Advisory we integrate your tax, business, wealth and lending as a prosperity engine, aligned with what matters most to you. With a clear roadmap, informed by data and backed by decades of strategic experience, we simplify the complex. We don’t offer pre-packaged solutions. We deliver tailored, end-to-end advice that reflects your reality and ambitions. You’ll work directly with senior advisers who listen deeply, think boldly and act with purpose. Feel cared for by our trusted team and curated network of financial and business specialists, as we empower you to make smart decisions and realise your potential, powered by numbers.
Frequently asked questions
What is a renovation loan in Australia?
A loan used to fund home renovations. Three common structures: a home loan top-up (extending your existing home loan), a construction loan (for major structural work with stage payments to the builder), or a personal loan (faster, higher rate, unsecured).
How does a construction loan work in Australia?
The lender approves the full project cost based on a fixed-price builder contract, then releases funds in 5 to 7 progress payments directly to the builder against signed progress claims. Interest accrues only on the drawn amount. Suitable for major structural work.
What is the difference between a construction loan and a renovation loan?
A construction loan funds new build or major structural work with staged progress payments. A renovation loan is a looser term that can refer to a home loan top-up or a personal loan used for smaller renovation work. The right structure depends on the scope of work.
Can I add the cost of renovations to my mortgage?
Often yes, through a home loan top-up. The new total loan amount is tested against APRA’s serviceability buffer (your rate plus 3 percentage points) and the lender’s DTI cap (typically around 6x gross income). Subject to those tests, smaller cosmetic projects are usually straightforward to add.
What is the interest rate on a renovation loan in 2026?
Home loan top-up: same as your existing home loan rate (often 5.1% to 6.5% in 2026). Construction loan: similar to home loan rates plus admin fees. Personal renovation loan: typically 8-12% in 2026 due to being unsecured and shorter term.
Do renovations add to the value of my home?
Some do, some don’t. Kitchens, bathrooms, adding bedrooms or living space, and energy-efficient upgrades typically return at or above cost. Pool installations, high-spec finishes for the suburb, and overcapitalising on a basic property often do not. Get an agent’s opinion before committing.
Are home renovations tax deductible in Australia?
Renovations on your owner-occupied home: no. Renovations on an investment property: may be partially deductible (as repairs) or claimed over time (as capital works). The distinction is important and often misunderstood. Get advice before treating a renovation as a current-year deduction.
Ready to talk?
If you would like a calm, no-pressure conversation about how this applies to your specific situation, we are here to help.
Please feel free to get in touch on 1300 925 081 or send an email to [email protected] if you’d like to book in a chat on the above or on other matters.
Disclaimer
This article contains general information only and has been prepared without considering your objectives, financial situation or needs. It is not personal financial advice, taxation advice or legal advice and should not be relied upon when making financial decisions. Before acting on any information, consider its appropriateness to your circumstances and seek professional advice where appropriate.